Hidden Fees and Fine Print: What to Watch for in Casino Withdrawal Terms
The fee is almost never called a fee. A casino withdrawal term sheet will mention a “processing charge,” a “currency handling adjustment,” or an “account maintenance condition,” and none of those phrases sound like money leaving your balance. They are. This article walks through where the cost hides. Bank wire charges, e-wallet percentages, card-network conversion markups, wagering requirements that lock a bonus balance entirely, and dormancy fees accumulate on dormant accounts. None of it is illegal. All of it is worded so the true cost stays invisible until the request is already submitted.
Where the withdrawal fee actually lives
Most casinos route withdrawal fees through payment rails. The cost appears on your statement, levied by the payment processor or your bank. Your casino account shows the withdrawal amount. The fee appears separately on your bank or processor statement.
Three rails do most of the work: card, e-wallet, and bank wire. Each carries different pricing, with differences large enough to matter on a single cashout, let alone a year of them.
| Payment Method | Fee | Processing Time |
|---|---|---|
| Bank wire | $15–50 per transfer | 1–3 business days |
| E-wallet | 1–2% or flat fee | 24–48 hours |
| Card network FX | 1–3% markup | Varies by processor |
| Processor FX | 2–5% additional markup | Included in above |
Wire fees come from the receiving bank, not the operator. The operator sends your money; your bank takes its cut before funds arrive. E-wallets like PayPal, Skrill, and Neteller charge a percentage that scales with withdrawal size. Cards occupy a middle position; the withdrawal often routes back through the card network, bringing its own pricing structure into play.
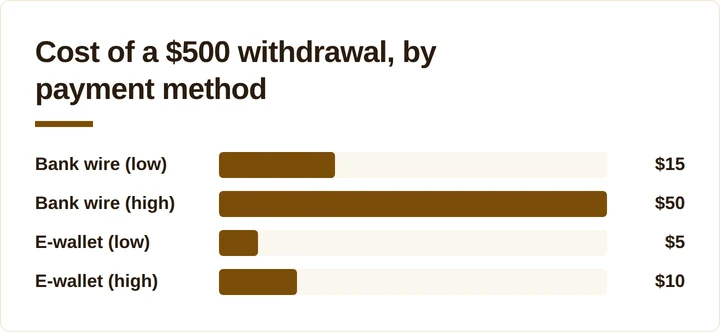
Take a $500 withdrawal. A wire fee of $15 to $50 works out to 3% to 10% of that amount, while an e-wallet charging 1% to 2% takes only $5 to $10. On this amount the wire is clearly the worse deal, both slower and more expensive. Somewhere past a few thousand dollars a flat wire fee starts winning over a percentage cut, since the flat charge stops scaling with the withdrawal size.
The currency-conversion trick
Currency conversion costs hide well because they’re split across two parties and neither is obligated to show you the combined cost.
Card networks charge roughly 1–3% on cross-border or currency-conversion transactions. This is the Visa and Mastercard rate from your cardholder agreement, disclosed in sections few people read. It’s a real cost, and it’s the smaller half of the problem.
Payment processors add their own conversion layer when they do currency conversion separately from the card network. The processor sets its own exchange rate, always lower value than the interbank rate. That gap can run 2–5% on top of the network fee. The difference appears as an exchange rate in your statement. Exchange rates appear in your account as currency adjustments, listed separately from line-item fees.
Stack the two together and a cross-border withdrawal loses value before reaching you. The combined cost can run 3–8% of the withdrawal. On a large withdrawal, the loss might easily reach several dozen dollars. It appears as a slightly worse exchange rate in your statement, with no separate fee line.
The practical test is to check whether the operator’s cashier page quotes a specific exchange rate before you confirm the withdrawal. If it does, compare that rate to the mid-market rate on the same day. The gap is your conversion cost. If the cashier page doesn’t quote a rate, the conversion is happening out of sight, and you should assume the markup is on the higher end of the range.
This conversion mechanism is what makes some casinos that accept Visa cheaper to withdraw from than others, even when the headline withdrawal fee is identical. The payment rail stays the same. The conversion handling varies by operator.
Wagering requirements as a withdrawal blocker
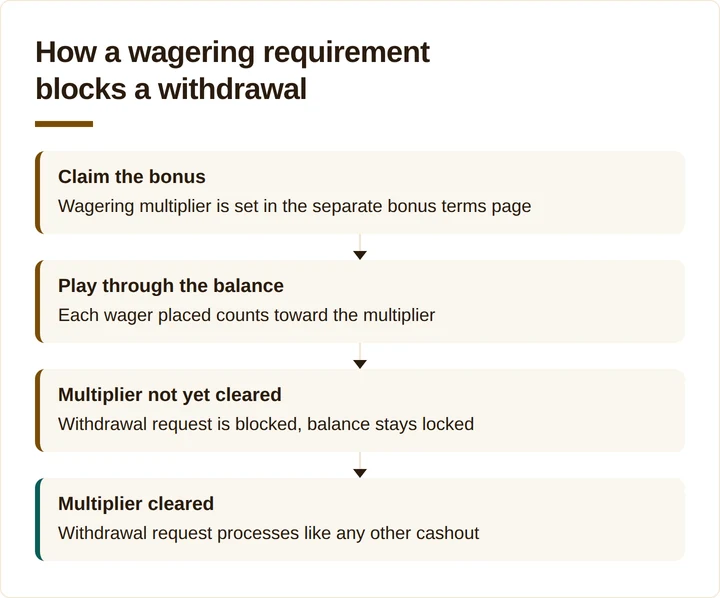
Wagering requirements function as a fee when they block a withdrawal. They appear as a bonus condition in the terms. Operationally, they lock your balance completely. The range is commonly 20x–40x the bonus amount. An unmet requirement blocks the withdrawal request entirely. The account balance stays locked to bonus funds until the multiplier is cleared. There’s no partial cashout.
A $50 bonus at a 30x wagering requirement means $1,500 in bets must be placed before any of that balance becomes withdrawable. Those are wagers, meaning bets placed and settled, and they do not count as deposits toward the requirement. Every wagering cycle carries its own house edge, so the real cost of accepting the bonus is paid across all that play. The bonus is the headline, and the requirement is the price attached to it.
The trickiest part is placement. The multiplier appears in the bonus terms page, away from the cashier page where you claim the bonus. You see a bonus offer in the cashier, click accept, and a wagering condition sits separately in the terms. By the time you try to withdraw, the requirement blocks the request, and the casino directs you to the terms page you didn’t read.
If you’re checking a wagering claim before trusting it, the verification process is usually documented separately from the bonus terms themselves, and it’s worth reading both before you deposit.
The fee nobody reads for
Dormancy fees appear on accounts you’ve abandoned. They accumulate monthly after an extended inactivity period. The pattern migrated from prepaid card issuers into gaming accounts under the same account-maintenance logic.
This fee matters more due to timing. Every other cost in this article hits during active play. The dormancy fee accumulates while you’re absent. You step away, the account sits dormant, and months later a monthly charge eats whatever balance remained. Most terms include no notification requirement. The clause appears as a single sentence labeled “maintenance fee,” disguising its penalty nature.
If you’re stepping away from an account for any length of time, the move is to withdraw the balance to zero before you go, or check the dormancy clause and note the trigger date. A modest balance sitting untouched can disappear entirely within a few years under monthly dormancy charges.
How to read the terms before it costs you
Four things to check before you deposit, in this order. Each one takes a couple of minutes and each one maps to a fee above.
The withdrawal fee schedule. Find the cashier page or the fees section of the terms and look for a stated schedule. If there’s no schedule, the fee is likely charged by the payment rail. Check the pricing with your bank, wallet provider, or card network. Each charges separately. Bank wire fees come from your bank, e-wallet fees from the wallet provider, card conversion fees from the network and processor.
The wagering multiplier. The multiplier appears on the bonus terms page, separated from the cashier page. Find the number before you claim anything. 20x and 40x are very different commitments on the same bonus amount, and the difference is the number of times your money has to cycle before withdrawal becomes possible.
The dormancy clause. Search the terms for “inactive,” “dormant,” or “maintenance.” If there’s a monthly charge and a trigger period, write down the trigger date. If you plan to leave the account alone, that date is when the balance starts shrinking.
The processing-time promise. This doesn’t carry a fee. It determines how long your money is exposed to every other cost in this article. Standard patterns are 24–48 hours for e-wallets and 1–3 business days for wire transfers. Anything longer than the stated window warrants a support ticket. Delays usually reflect verification queues within the casino’s system.
Bottom line
Nothing in this article describes anything illegal or unusual. Wire fees, e-wallet percentages, card conversion markups, wagering multipliers, and dormancy charges are all standard terms, disclosed somewhere in the paperwork.
The issue is placement. The fee appears as a “processing charge.” The conversion cost shows as an “exchange rate.” The wagering lock hides as a bonus condition on a separate page. The dormancy charge sits in the terms as a “maintenance fee,” hidden unless you search for it. By the time you submit a withdrawal, the cost is locked in, and the answer was in the terms all along.
Read the four items above before you deposit. This is your only defense.
FAQ
What’s the difference between a card-network FX fee and a processor’s conversion markup?
The card-network fee is Visa or Mastercard’s charge on cross-border or currency-conversion transactions (typically 1–3%), disclosed in your cardholder agreement. A processor’s conversion markup is separate. When the processor does its own currency conversion, it sets its own exchange rate. That rate is worse than the interbank rate by 2–5%, adding margin on top of the network fee. Both can apply to the same withdrawal. Only the card-network fee typically appears explicitly labeled as “fee.”
What happens to a bonus balance if the wagering requirement isn’t cleared?
The balance stays locked. An unmet wagering requirement blocks the withdrawal request entirely. High multipliers mean substantial total wagers required before withdrawal. Until then, the funds sit in the account for further play only. Cashout remains impossible.
Are dormancy fees charged by the casino or by the payment provider?
It depends on the account. Monthly dormancy fees (typically several dollars to fifteen per month) come from prepaid card issuers and financial-services accounts, appearing in both payment-provider and gaming-account terms. The clause usually appears as a single sentence phrased as “maintenance fee,” triggered after several months without activity. Check which account the balance sits in and read that specific account’s full terms.
Can a casino charge a withdrawal fee that isn’t listed in the terms?
A stated fee schedule is the operator’s own charge, and it should be listed. What often isn’t listed is the cost charged by the payment rail. Bank wire fees come from the receiving bank, e-wallet fees from the wallet provider, and card conversion markups from the network and processor. These belong to the payment system, appearing in the rail’s fee schedule instead. They still come out of your withdrawal.
Does a faster withdrawal method always cost more?
No. E-wallets are faster (24–48 hours once approved) and cheaper on smaller amounts, typically 1–2% versus a modest fixed wire fee. Wire transfers only become competitive on larger withdrawals, where a flat fee beats a percentage. Speed and cost vary by amount and rail choice, with no fixed rule.
Foundation Check
Three things to confirm for yourself, in the platform's own documents, before you act on anything above. This is a checklist, not a score.
- Search the terms for a withdrawal fee, an inactivity fee and a currency-conversion charge, each stated separately.
- Check whether a free withdrawal allowance exists and how often it resets.
- Confirm which side absorbs the payment provider's own charge — the platform or you.